Volume Analysis | Flash Update – 9.21.26
Decision Candle on the Front Lines
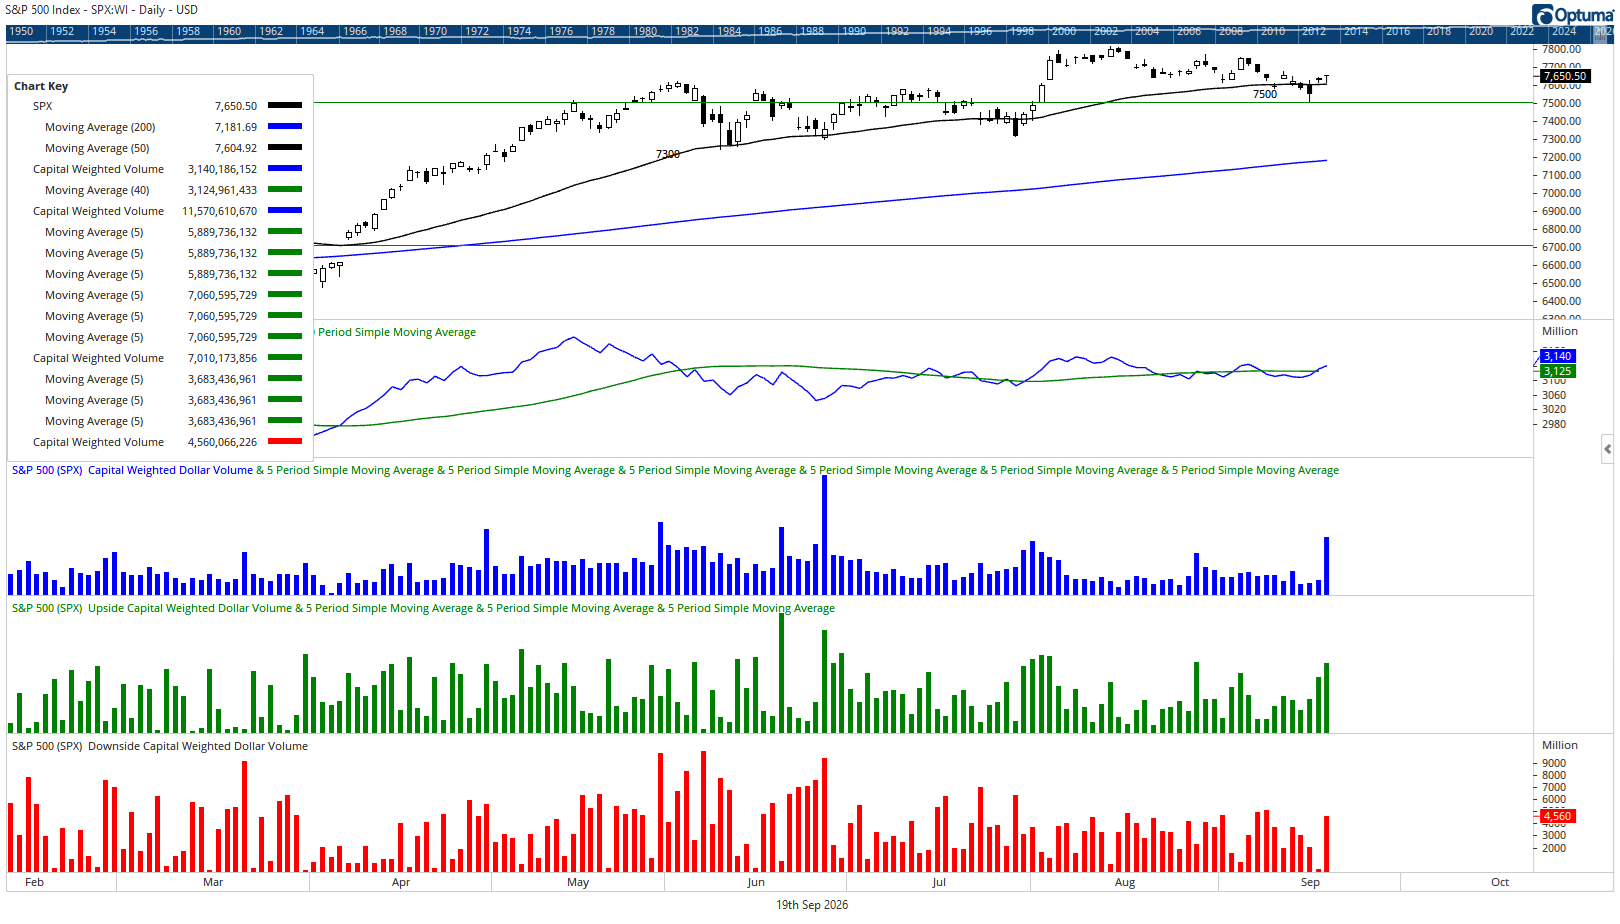
The market entered the week on uncertain footing, then reached an important crossroads following the Federal Reserve announcement. After an initial positive reaction early Wednesday, the S&P 500 reversed lower, tested and kissed intermediate support near 7500, then held the line. The follow-through was notable the next day. Thursday opened with a strong upside gap and finished as a 95% Capital Weighted Dollar Volume inflow day on typical volume. However, even that notable advance carried its own battlefield nuance, as Thursday closed much higher than Wednesday, but still finished below its own opening level.
Friday was conviction day. Capital flows surged to their strongest levels since the June 26th all-time high, 60% of capital flows registered as inflows. The S&P 500 opened, closed, and finished at its daily high near 7657, which represents short-term resistance. This pattern forms a decision candle, AKA a dragonfly doji. In this context, 7657 becomes the battlefield line. If bulls push through this level with continued sponsorship, that may mark the beginning of the end of September’s weakness. If they fail, another retest of support remains possible.
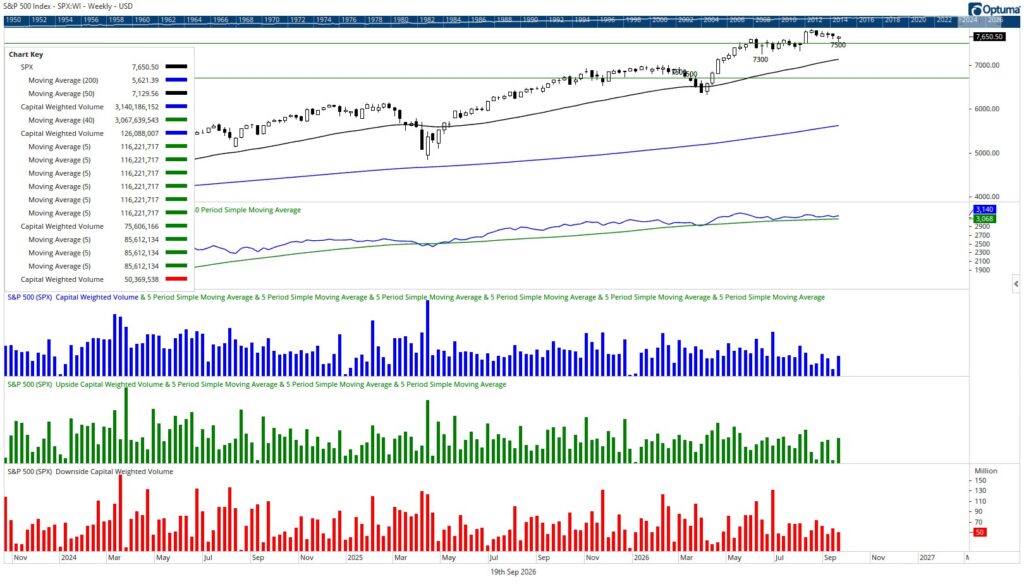
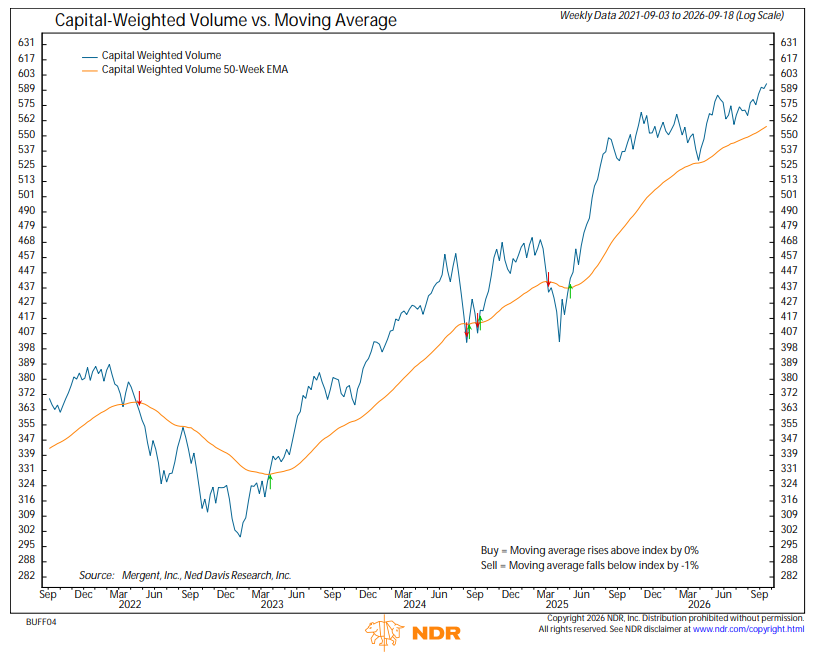
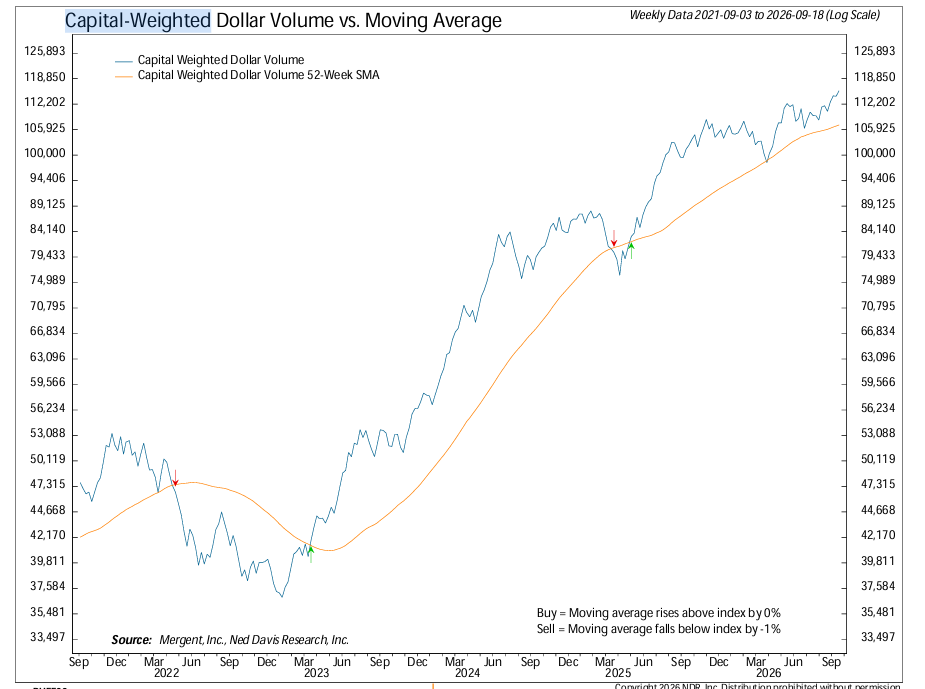
For the week, capital flows were stronger than in recent weeks but still only average overall. S&P 500 Capital Weighted Dollar Volume finished with 60% inflows, while 59% of Capital Weighted Volume traded to the upside, even as the S&P 500 price index slipped slightly, down 0.08%. This is constructive under the surface. Price looked indecisive, but volume and capital flows leaned supportive. The trends of both capital-weighted volume and dollar volume are both slowly churning out new all-time highs.
This directly ties to the Second Half Volume Analysis Outlook. The market has been in a transition tape, not simply a narrow bull market continuation and not yet a fully confirmed broad market advance. Leadership is rotating, dispersion is rising, and selectivity matters. In our work, price tells us what investors have done, while volume tells us whether they did it with conviction. Volume remains the fuel of the market even as broadening fades.
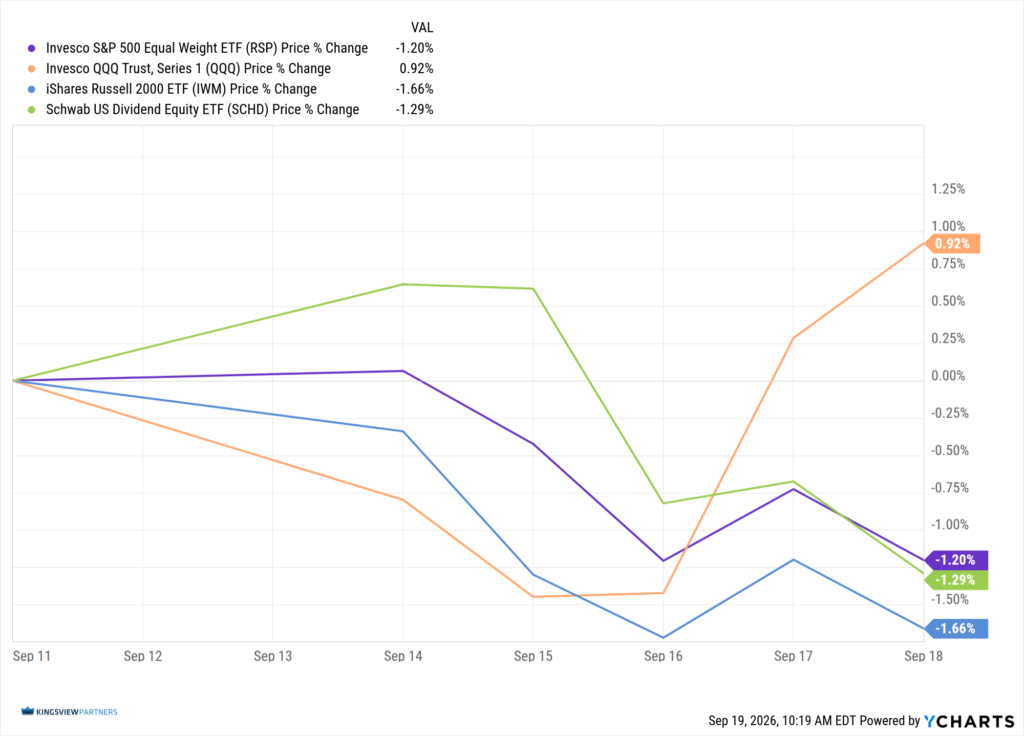
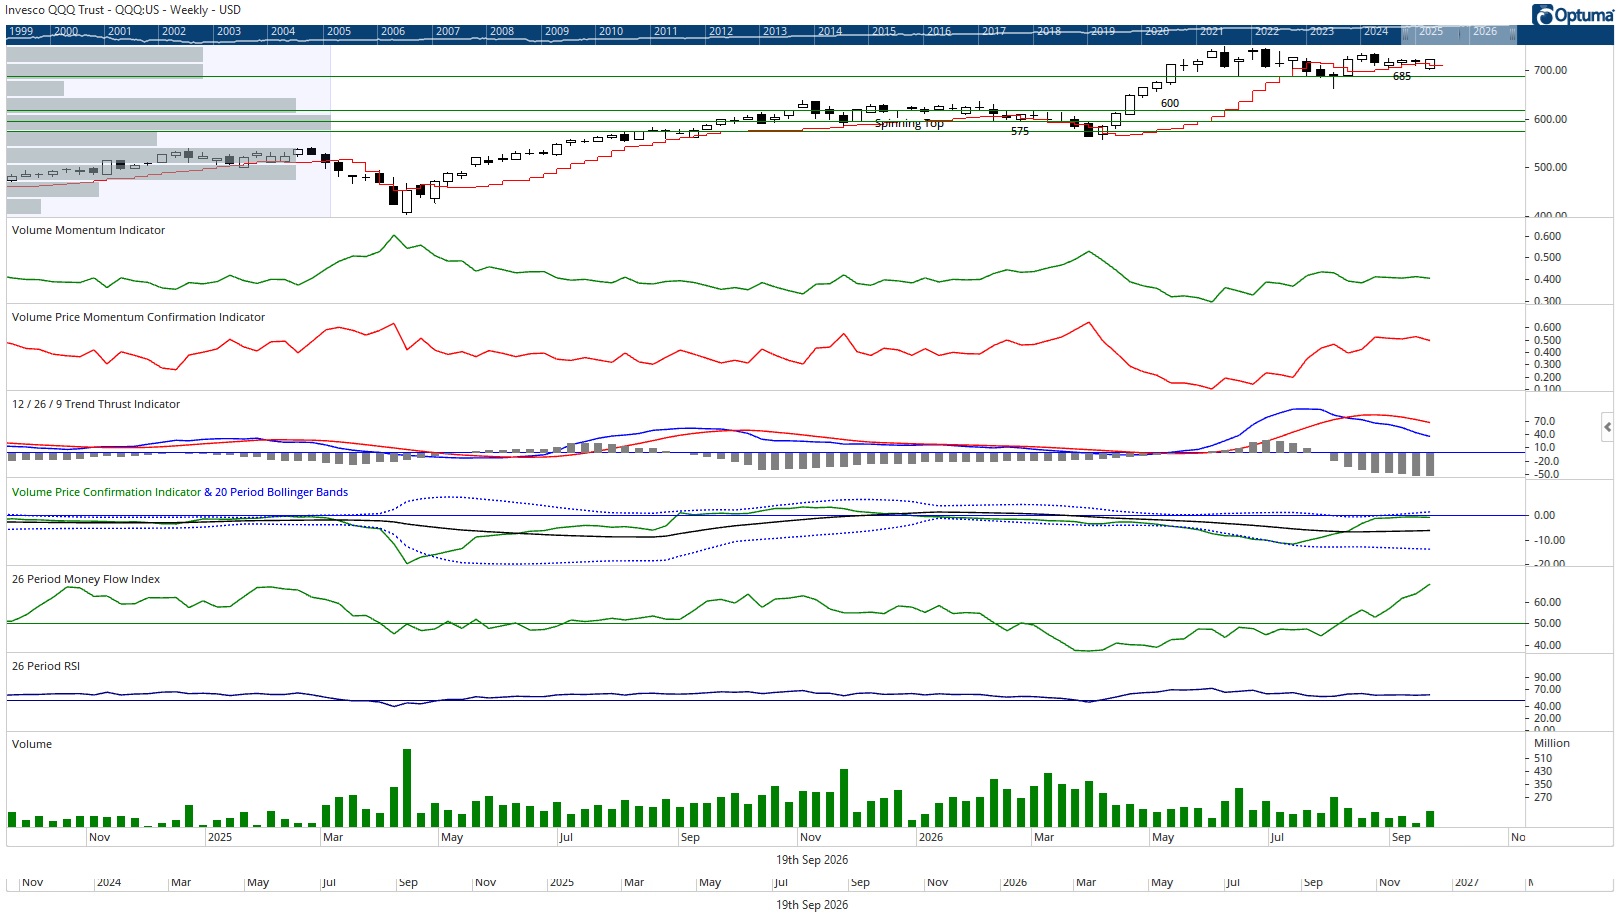
The generals, represented by the Invesco QQQ Trust Series 1, continued to lead the advance. After testing 700 support earlier in the week, the generals closed on their weekly high near 721. That level is important because it sits near the upper end of the late August trading coil, with roughly 721 resistance and 700 support. The volume picture within this coil has become more constructive. The generals are not yet in open field, but they have stopped retreating and are attempting to reassert command.
The troops, represented by the iShares Russell 2000 ETF, remain the most vulnerable unit. They fell -1.66% on the week. On Wednesday, the troops retreated back to their trenches near 281 before rallying, then faltered Friday to close near 284. The 280 level now becomes crucial. If the troops lose 280, small caps could be lost from the bullish field. In the Second Half Outlook, the iShares Russell 2000 ETF was highlighted as an important broadening unit, with a critical trendline support level near 270 and rising.
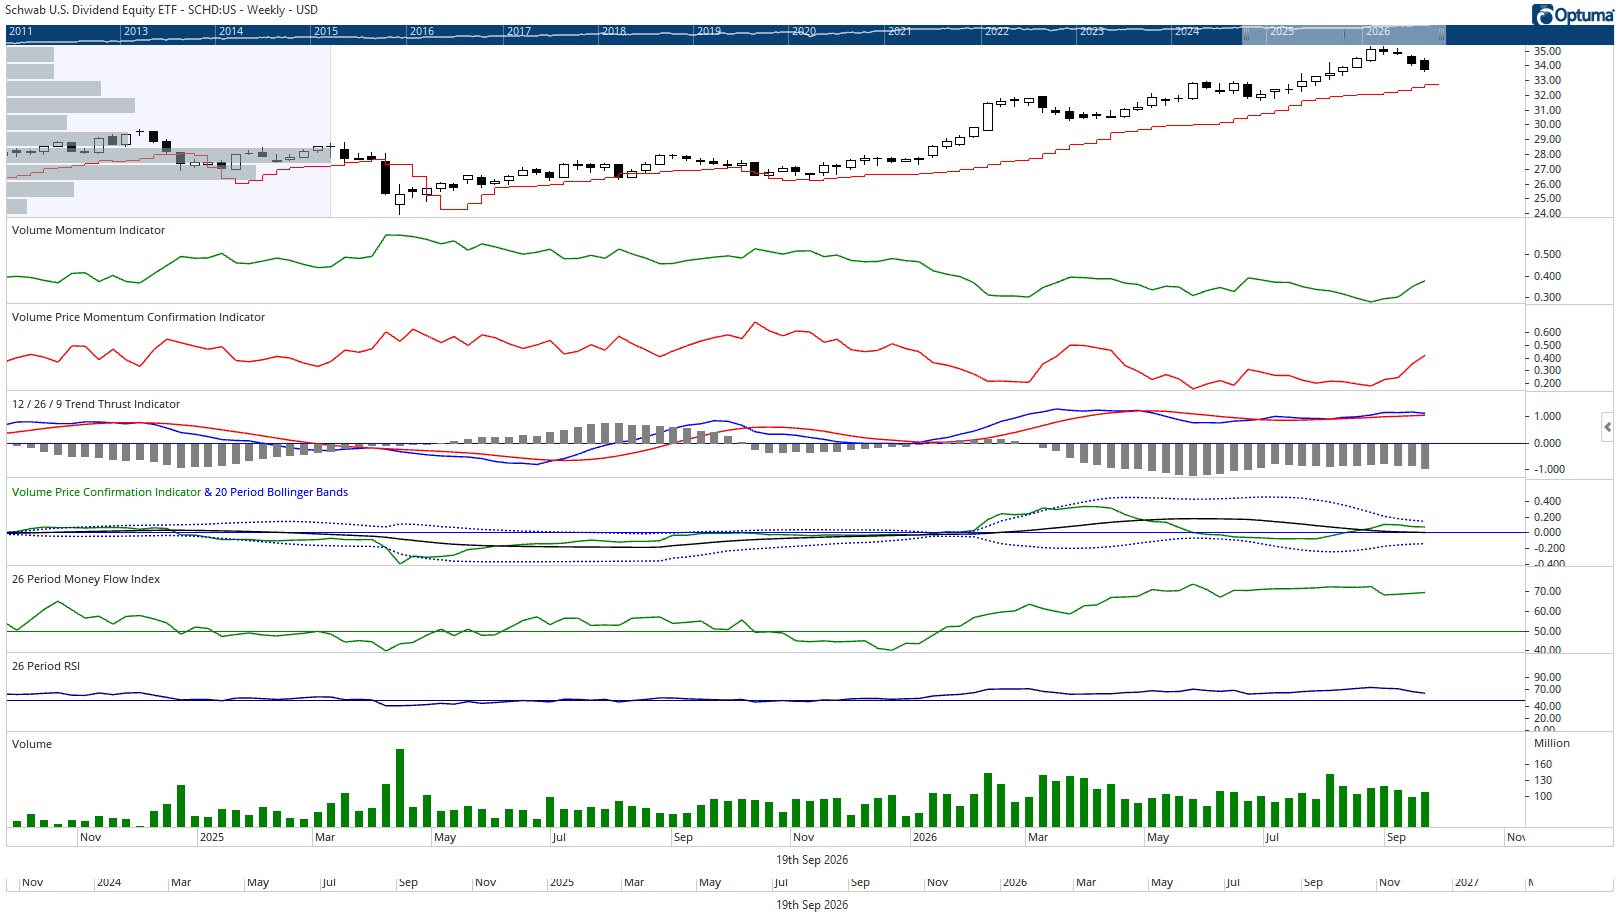
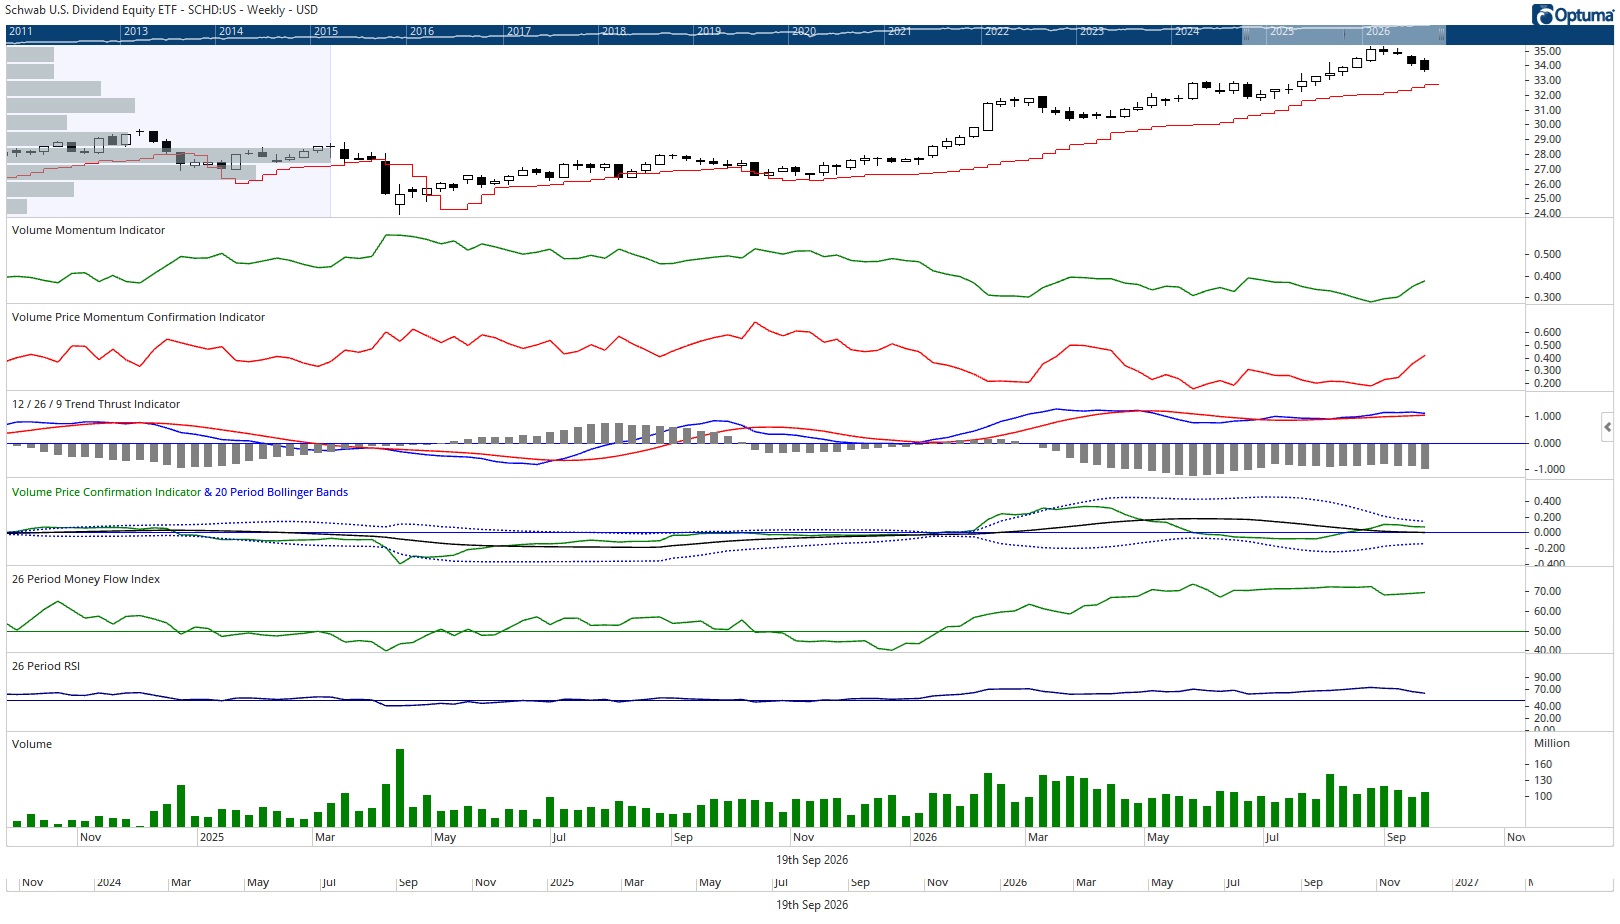
The lieutenants, represented by the Invesco S&P 500 Equal Weight ETF, continued to make lower highs and lower lows, closing down -1.20%. Their next support line sits deeper near 205. Likewise, the dividend brass commanders, represented by the Schwab U.S. Dividend Equity ETF, continued their recent consolidation from the July breakout and August peak, falling -1.29%. The broader belly of the market is not collapsing but is no longer leading.
This is the key tension in the broadening campaign. The generals are trying to reassume command, but the troops, lieutenants, and brass commanders are not yet marching in formation. In the spirit of And Then There Were None, the army has not disappeared. But several regiments are back in the trenches, waiting to see whether the generals can break the ridge and inspire a broader counterattack.
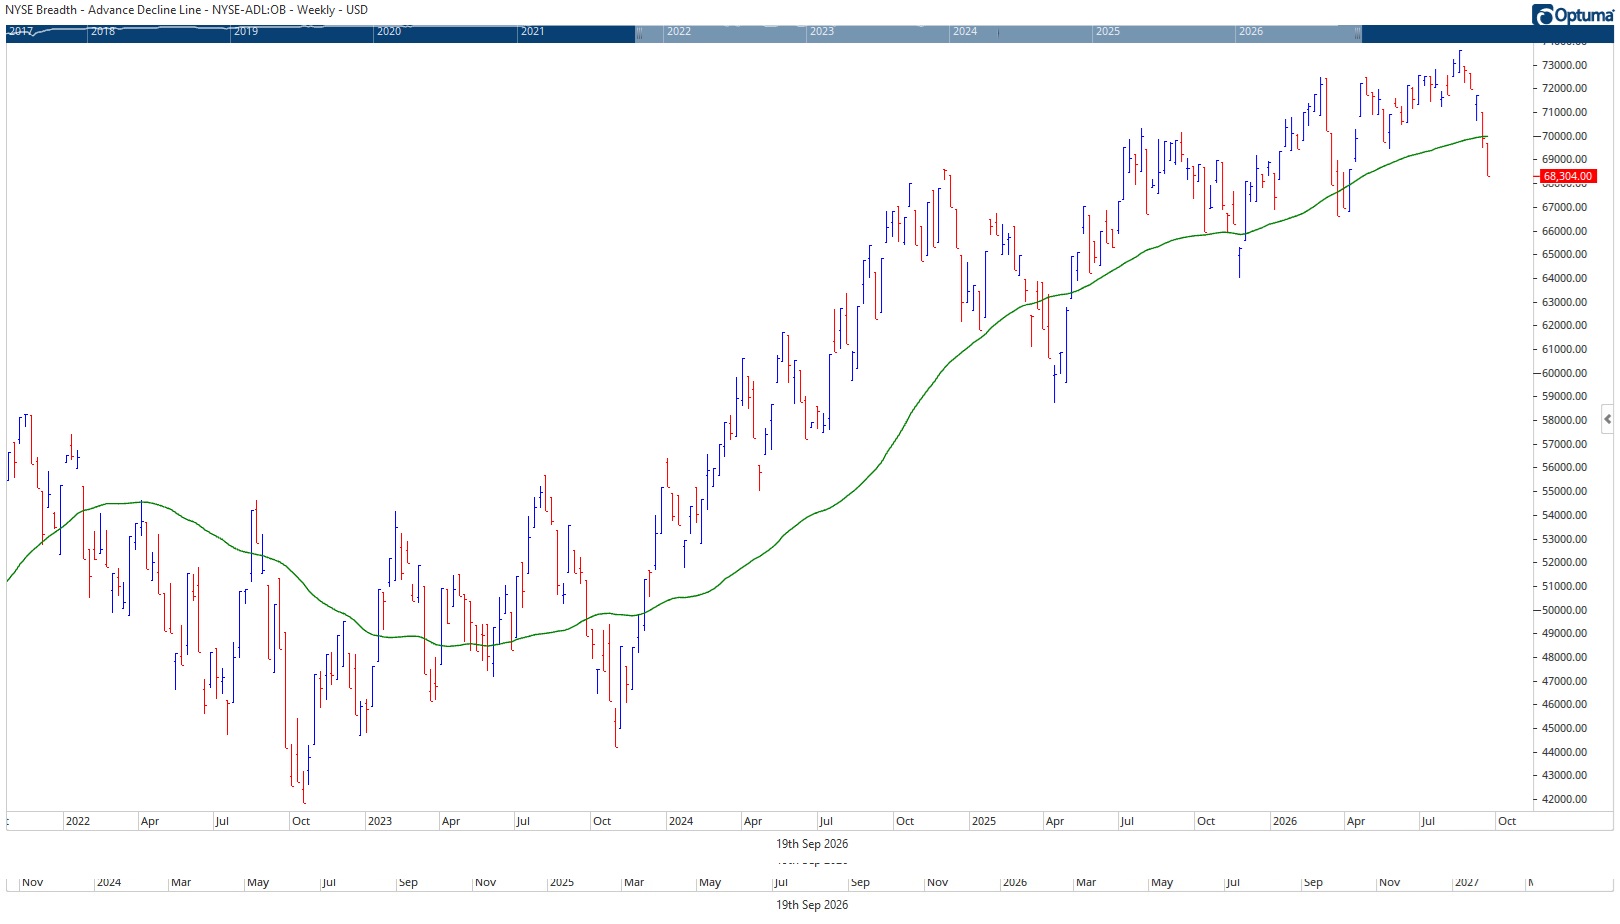
The most concerning threat to the broader market recovery is the NYSE Advance Decline Line. Last week, breadth fell back to its trend line. This week, it clearly broke its uptrend. This once bullish leading indicator has now turned neutral. That does not automatically mean the campaign is lost, but it removes one of the stronger confirmations behind the broadening thesis.
This holds significance as the broader participation story has been the bright spot of 2026. The Outlook noted that the market had been evolving from And Then There Were None toward And Then There Were Some, with more stocks participating and the opportunity shifting toward wider participation rather than simply chasing growth or value. Breadth now needs to stabilize quickly if that constructive rotation story is going to remain intact.
The VFGU posture remains consistent with this environment. The Q3 framework emphasizes broader leadership, improving market breadth, dividend growth, international participation, quality companies, and diversified factor exposure. It also describes the posture as fully invested, diversified leadership, managing risk objectively. That remains the right command posture for a market where the evidence supports participation, but not complacency.
The Iran war continues to frame the cross-asset battlefield. Recent reporting shows renewed discussion around Strait of Hormuz routes and shipping access, but also continued uncertainty around broader U.S., Iran negotiations and regional supply disruption. Oil futures recently ended a volatile week little changed, with traders focused on Middle East supply disruptions, shipping restrictions through Hormuz, and damage to Saudi Arabia’s East West pipeline. Separate reporting indicates Iran and Oman have discussed new Hormuz routes, but the waterway remains a strategic pressure point rather than a fully secured passage.
Oil, represented by NYMEX Brent, met heavy resistance near 110 and stayed completely within last week’s wide range, closing near the prior week’s closing level. The energy front remains active but undecided. Despite a rally in the U.S. Dollar Index, gold and silver both closed higher on the week. However, both made lower lows intraweek, keeping their short-term downtrends intact.
The S&P 500 now faces support near 7500 and resistance near 7657, with 7800 still the larger upside objective. A push through 7657 on continued inflows would strengthen the bullish case and suggest September weakness may be ending early. Failure at 7657 would likely keep the market in test and retest mode. Major S&P 500 support resides near 7300.
Overall, this week produced a subtle but important improvement beneath the price surface. The index slipped slightly, yet Capital Weighted Volume and Capital Weighted Dollar Volume leaned positive. The generals held support and closed strong. The troops remain vulnerable. The lieutenants and brass commanders are consolidating. Breadth broke trend and is now the key concern. This is not a clean victory for the bulls. It is a crossroad.
Risk Command
This week improved the tactical picture, but it did not deliver an all-clear signal. Capital flows improved, the S&P 500 defended 7500, and the generals reclaimed a weekly high. However, breadth broke trend, the troops remain vulnerable near 280, and the belly of the market has yet to rejoin the generals’ attempts to advance.
A disciplined risk management approach remains the proper command posture. The bulls need the S&P 500 to break and hold above 7657, then challenge 7800. The bulls’ leadership, the generals, must continue holding above 700 and eventually push through 721 to 735. The troops must defend 280. The lieutenants and the brass need to stabilize to restore the broadening campaign.
If volume and capital flows continue to improve while breadth stabilizes, the bulls may regain stronger control. If breadth deteriorates further or support fails, defensive positioning could take priority.
For now, the generals are attempting to lead again, but the broader army has not fully followed. The decision candle near 7657 now marks the battlefield. In markets as in war, the objective is not to win every skirmish. It is to defend critical ground, follow the flow of capital, and manage risk before it manages you.
Grace and peace,
BUFF DORMEIER, CMT
Updated: 9/21/2026. Historical references do not assume that any prior market behavior will be duplicated. Past performance does not indicate future results. This material has been prepared by Kingsview Wealth Management, LLC. It is not, and should not, be regarded as investment advice or as a recommendation regarding any particular security or course of action. Opinions expressed herein are current opinions as of the date appearing in this material only. All investments entail risks. There is no guarantee that investment strategies will achieve the desired results under all market conditions and each investor should evaluate their ability to invest for the long term. Investment advisory services offered through Kingsview Wealth Management, LLC (“KWM”), an SEC Registered Investment Adviser.